Wednesday, September 16, 2026

KPMG Australia Scandal Shows Misconduct Rules Need Strengthening - KPMG under investigation over audits for Prax’s State Oil arm


KPMG Australia Scandal Shows Misconduct Rules Need Strengthening

Sept. 15, 2026

As Australia considers breaking up its Big Four firms because of renewed scrutiny, policymakers should recognize that separating audit from consulting is only part of the answer. They must also address misconduct within auditing and ensure the actors responsible bear financial consequences. Australia’s scandal may also prove a useful warning for US policymakers — and its response may offer a useful test bed.

Policymakers should focus closely on how audit firms win business. Regulators should require stronger controls on who can access confidential client information, independent review of all major sales pitches, and compensation arrangements that ensure improper gains are recoverable after the responsible partners leave the firm. Such measures would target a problem that structural separation alone can’t solve.

The allegations in Australia make the gaps clear. For example, KPMG Australia is accused of using confidential information obtained from one client to pursue audit work from others. An audit-only firm could do that — it would no longer have consulting work to cross-sell, but it still would have information that competitors don’t, while competing for audit clients.

When the same firm is tasked with both independently scrutinizing a company’s financial statements and selling that company advisory services, the incentives can compete. Entity-level separation can reduce those conflicts by making the auditor less financially reliant on the client for work unrelated to the audit in front of them.

That solution, however, doesn’t reach every source of potential misconduct inside the audit business. Indeed, US regulators have already seen a variant of this broad problem.

In 2019, the Securities and Exchange Commission reached a settlement with KPMG’s US firm over misconduct involving confidential information regarding inspections by the Public Company Accounting Oversight Board. According to the agency, a former KPMG partner had attempted to use improperly obtained information about the regulatory inspection of another accounting firm to help KPMG win audit business.

The US episode is instructive because spinning off a consulting firm wouldn’t have prevented it. The misconduct arose from competition within the audit sector itself. Structural separation can reduce conflicts between divisions, but it can’t eliminate the natural temptation to turn confidential information into an advantage over rivals.

Australia has already moved in this general direction for tax advisers. New legislation increases penalties against individual agents for unethical conduct and can impose liability on partners as well. That is a strong policy recognition that deterrence works best when consequences reach the people making the offending decisions, rather than falling purely at the firm level.

But penalties against individuals aren’t the same as recovery of the economic spoils of misconduct. A partner who wins business improperly may receive compensation stemming from those actions years before the conduct is uncovered. Regulators should therefore pair individual sanctions with required compensation arrangements that consider how bonuses or profit distribution can remain attributable to specific transactions — and thus recoverable when misconduct is found, even after a partner leaves the firm.
Regulators should scrutinize whether audit firms are independent from their clients, and also how they compete for new business.
Regulators should scrutinize whether audit firms are independent from their clients, and also how they compete for new business. 
Photographer: Brendon Thorne/Bloomberg via Getty Images

Imagine a partner who helps win business through improper use of confidential information, receives compensation reflecting that success, then leaves the firm long before regulators can act. Years later, a firm-level penalty may be paid by current partners, including people who had nothing to do with the misconduct and never shared in the rewards. The former partner, meanwhile, may have already collected the relevant bonus or profit distribution.

Firms should remain responsible for supervision and their culture and practices, but institutional liability and individual financial accountability are different things. And each places different pressures on the relevant actors in the decision-making process. Regulators should be attentive to both.

There needs to be a more targeted response. Australia’s proposals already contemplate stronger safeguards for confidentiality. That leaves a question over whether those obligations will translate into something regulators can test.

Regulators should scrutinize whether audit firms are independent from their clients, and also how they compete for new business. Firms auditing public companies should be required to prove that access to confidential client and regulatory information is limited to legitimate professional needs, that exposure within the firm is tracked, and that sensitive information can’t migrate from an audit team to a sales pitch — even informally.

Major proposals for new audit work should at minimum receive independent review by someone whose compensation and performance metrics aren’t tied to winning the contract. That review should ask basic questions such as where the information supporting the pitch came from and what information is being leveraged. Regulators could then test controls through direct inspections of a random sampling of bids and related records.

Properly calibrated, none of this would require preventing auditors from using their experience or sector knowledge when pursuing new clients. The relevant line should be drawn between expertise gained through experience and confidential information entrusted to the firm for a specific and limited purpose. Separating audit and consulting should be seen more as a tool to prevent privileged access from becoming a competitive advantage rather than a cure-all.

Part of making sure the economic incidence of misconduct falls on the right parties would entail requiring firms to structure partner compensation so that portions tied to misconduct remain recoverable. The goal isn’t to punish every partner for every firm failure, but to key recovery to proven wrongdoing or serious supervisory failings, with an opportunity to contest responsibility.

Forward-looking compensation agreements could keep relevant payouts recoverable for a set period even after a partner leaves the firm. Said agreements should supplement penalties at the firm level rather than replace them.

Policymakers facing similar auditor confidentiality issues in other countries, including the US, should pair structural changes with rules aimed directly at the gaps misconduct has evinced. That requires placing controls over how confidential information is used when firms compete for business and modifying compensation arrangements to keep improper gains recoverable.

Breaking up the Big Four may change what firms sell. But policies also need to change how they win business — and who pays when lines are crossed.

Andrew Leahey is an assistant professor of law at Drexel Kline School of Law, where he teaches classes on tax, technology, and regulation. Follow him on Mastodon at @andrew@esq.social.


Inside the scandal that destroyed KPMG’s reputation

A whistleblower, a secret document and a self-inflicted scandal that’s cost hundreds of jobs and shattered reputations. Today, how KPMG blew itself up, with the journo who’s been breaking all the scoops, our own Tansy Harcourt.


Ex-KPMG chief collects $4m payout amid firm’s devastating audit scandal

Former KPMG exec Eileen Hoggett sues firm seeking documents

KPMG begins brutal 500 jobs cull amid audit scandal fallout

Labor government extends ban on KPMG work for public service

KPMG partners lied to deputy general counsel, parliamentary inquiry hears


This episode of The Front is presented by Claire Harvey, produced by Kristen Amiet and edited by Tiffany Dimmack. Our team includes Lia Tsamoglou, Joshua Burton and Jasper Leak, who also composed our music. 


Leaky ship KPMG retains $126m in contracts for top-secret AUKUS work

KPMG has kept its keys to Australia’s most classified nuclear secrets – worth $126m to the firm – even after admitting it repeatedly stole and shared confidential client information.


KPMG under investigation over audits for Prax’s State Oil arm 

 Big Four accountant, PKF Littlejohn and an unnamed individual to face FRC probe 

The KPMG logo displayed on the exterior of a building at Canary Wharf financial district. KPMG said it would ‘co-operate fully’ with the Financial Reporting Council ‘to conclude this matter as quickly as possible’ © Reuters

The UK’s accountancy regulator has opened an investigation into KPMG over the audits and financing arrangements of State Oil Limited, part of collapsed oil company Prax Group. 

The Financial Reporting Council said on Friday that it would use two separate procedures to probe State Oil’s accounts between 2021 and 2024, investigating KPMG for its work on the company’s books as well as an unnamed individual accountant.
The investigation will also look at the audit of State Oil performed by mid-tier accounting firm PKF Littlejohn in 2024, which took over from KPMG that year. 
Prax Group, and its Lindsey oil refinery in north-east England, plunged into insolvency in 2025, putting more than 400 jobs at risk in a blow to the UK’s struggling oil refining industry. 
The collapse provoked a fierce backlash from the UK government, which demanded an investigation into Prax’s “wealthy owner” and said that the company had been “unable” to answer questions from the government about its finances. 

Privately held Prax was founded in 1999 by chief executive and chair Sanjeev Kumar Soosaipillai and his wife Arani Soosaipillai with a single petrol station near St Albans. It expanded into a sprawling conglomerate spanning refineries in the UK and South Africa, petrol stations and a trading business. 

Separately from the FRC investigation, Sanjeev Kumar Soosaipillai is being sued by administrators who allege that he told employees to fake £334mn worth of invoices as part of what they called a “web of deceit” that enabled Prax to borrow from Wall Street lenders. 
The claim alleges that Soosaipillai asked senior employees to submit “fictitious invoices” for sale to support the group as it battled costly refinery works.

Soosaipillai has denied knowing about the fictitious invoices until being told about them in May or June 2025, and denies giving instructions that they should be created, according to documents filed with the court by his legal team. He told the FT in June that he had “always acted in good faith” to protect the refinery. 
KPMG said it would “co-operate fully with the FRC to conclude this matter as quickly as possible”. PKF Littlejohn said: “We take our professional responsibilities and the quality of our audits extremely seriously. We will co-operate fully with the FRC throughout its investigation.”

Man pleads guilty to filing bogus returns to get refunds; got $7 million

 DOJ announces creation of nationwide Fraud Detection Center

 
FBI investigating online company that advertises scans of 153 million driver’s licenses from the US and Canada
 
Europol announces that the US, Hungary, Romania, and Bulgaria have taken down a botnet that has affected 11 million computers and that has been running for twenty years
 
Canada sees fraud losses in the first six months of the year reach $351 million; nearly half of that is investment fraud (meaning crypto romance fraud)
 
Does shutting down huge scam compounds eliminate fraud?  Its hard not to be happy that these massive centers that kidnap people and rob people across the world are being closed down.  But my experience is that when large fraud centers are closed a raft of small ones quickly emerges.  And former employees and managers have developed the skills and expertise to run these new operations.  It looks like these frauds are simply moving to different countries or setting up shop clandestinely in smaller units. So the fight against fraud has to continue.
 

Fraud Studies: Here are links to the studies I’ve written for the Better Business Bureau: puppy fraudromance fraud; BEC fraudsweepstakes/lottery fraud,  tech support fraudromance fraud money mulescrooked movers, government impostersonline vehicle sale scamsrental fraud, gift cards,  free trial offer frauds,  job scams,  online shopping fraud,  fake check fraud and crypto scams
 
Fraud News Around the worldFTC and CFPBHumorBEC Fraud 
Benefit TheftScam CompoundsRansomware and data breachesIRS and tax fraudATM Skimming                                                       Jamaica and Lottery FraudRomance Fraud and Sextortion 

'Can you do my tax?': ATO, Services Australia prep for AI agents

 'Can you do my tax?': ATO, Services Australia prep for AI agents 

Aussies will use agentic tech to access key services, officials say


Australians can expect to ask their own personal AI agents to complete tax returns and access government services for them in the future, officials from the Australian Taxation Office (ATO) and Services Australia said on Monday.

Artificial intelligence agents, otherwise known as agentic AI, are AI models which can autonomously complete multi-step tasks on behalf of their users.

While most consumers have had little exposure to AI agents, representatives from both the ATO and Services Australia told the Gartner IT Symposium/Xpo on the Gold Coast that they foresee taxpayers' AI agents directly interacting with government AI agents in the future.

Services Australia deputy CEO, Jonathon Thorpe, said he could see a future in which an individual's AI agent "potentially could do a fairly good job" of using their personal information and context to access the right government services.

"We're seeing – and I think anyone would attest this in most industries – that increasingly customers are experimenting with agents in their everyday life," he said.

"Increasingly, we're going to have to think about what that means in the context of government service delivery.

"... If you start to think about agentic systems or multi-agent systems, you could see a moment in time where you've got society, consumer, customers starting to do this themselves."

The ATO's chief information officer Mark Sawade agreed.

"I think we'll be in a world where we'll be eventually talking to our personal agent, saying, 'All right, it's now mid-July, can you please just fill out my income tax return?'

"And the personal agent will talk to one or more other agents through the government ecosystem," he said.

'We're not there yet': The security and liability concerns

Both Thorpe and Sawade admitted government agencies were still a long way from directly engaging with AI agents used by Australians, due to current technological limitations and security and liability concerns.

"Where it starts to run into a lot of trouble really quickly is proving who someone is," said Thorpe from Services Australia.

"And at the moment, we don't have the plumbing necessary for agentic identity, particularly in the consumer and citizen space.

"I think we'll solve it, but it's not here yet."

A key challenge is "liability and responsibility" if things go wrong, Thorpe said. 

"What happens if you set up an agent and you didn't quite set the appropriate guardrails? What's government's responsibility in that interaction?" he said.

Sawade agreed that government services are "a long way" from embracing AI agents from individual users, and identity issues are "one of the key things we'll need to solve".

"But if we're not thinking about how do we get there now, and the types of building blocks we'll need to put in place, it'll be an incredibly long time before I think we'll be ready to have government services that are safely and securely and transparently interacted with in in that way," he said.


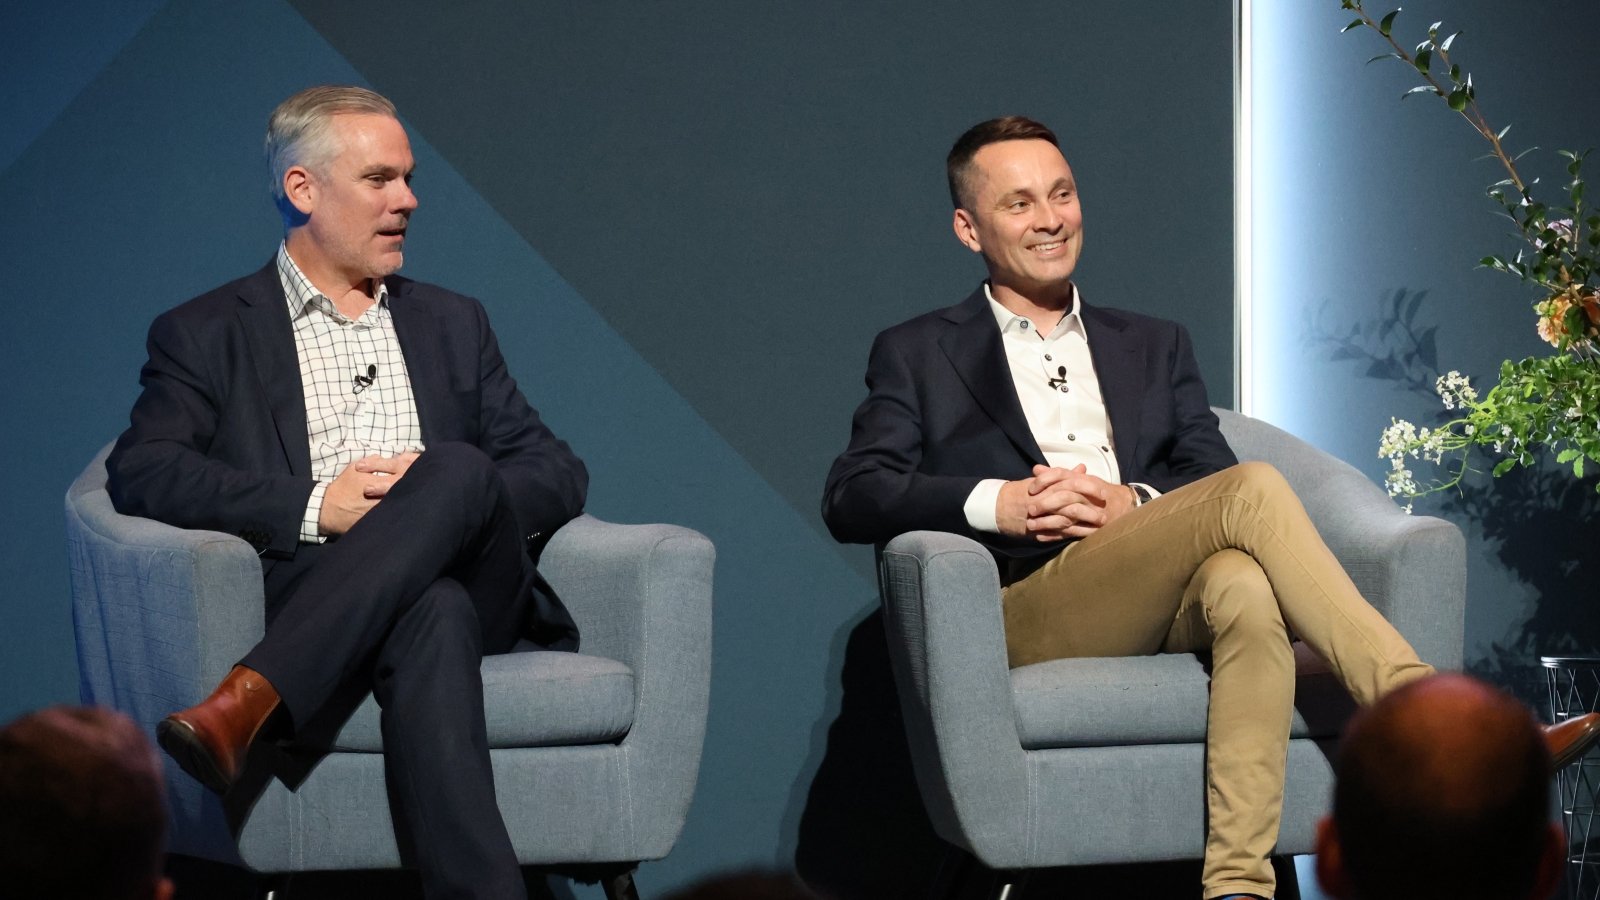
ATO chief information officer Mark Sawade (left) with Services Australia deputy CEO Jonathon Thorpe (right) at the 2026 Gartner IT Symposium/Xpo. Image: Gartner / Supplied

Internal agentic opportunities likely 'a lot easier'

Thorpe from Services Australia, which delivers government programs such as Centrelink and Medicare, said he saw agentic AI opportunities within organisations as "in some ways ... a lot easier".

"That being said, I think we'll still need to work out: Are they on organisational charts? Who's responsible for the agent deployment? How do you deal with machine speed assurance?"

Thorpe added that Services Australia is "quite cautious" about how it applies generative AI, and sees the technology "as an opportunity to evolve that service and make it better, not replace it".

"I do think there's places where agentic can play a better role, and that could be assisting our staff," he said.

"I don't think it's in front of our staff – I think it's I think it's actually behind it.

"How AI can support public servants to do a better job and better inform the community about what obligations, payments, and services are available to them."

These techniques are among what Services Australia is "looking at now as we transform our contact centre", Thorpe added.

Services Australia released its first AI and automation strategy in May 2025 – which did not explicitly mention agentic AI – after publicly defending its trials of AI technology.

The organisation's national manager of enterprise architecture and cloud engineering, Darren Vrettas, was gifted tickets to attend IBM's Agentic AI Summit in November 2025, according to Services Australia's gift disclosures.

Sawade from the ATO, which this year warned taxpayers against using AI in their tax returns, told the conference that his organisation had put generative AI "in the hands of as many of our staff as we can" to help with administrative tasks.

But he added the ATO workforce has "an appetite to go faster".

"They would like to be able to see where we could automate a whole range of different opportunities to give a better experience for both our staff and in terms of our mission," he said. 

"We've had to be really, really careful about ensuring that we've got the right foundations in place. We've got transparency, we've got observability, and we've got a way of industrialising our use of AI with a lot of confidence.

"Because, quite rightly, we'll come under a lot of scrutiny for where we choose to start using AI – not so much in those administrative-type tasks – but where we are thinking about how it might add real value in those rewired business processes inside the ATO."

Gartner analyst Dean Lacheca said, "Success with agentic AI will depend on modern governance, workforce readiness, and the ability to redesign business processes, while creating an adaptable foundation for future innovation."


Interdependency and the ATO: A tale of two views

The ATO is placing more emphasis on whether a relationship displays a “strong commitment to a shared life” in the most recent Private Binding Rulings on interdependency, Michael Hallinan, special counsel for SUPERCentral, said.


Hallinan said the primary issue of whether the relationship between the adult child and the parent is one which is a “close personal relationship” but more importantly whether that relationship exhibits a “strong commitment to a shared life”.

“Defining interdependency has four requirements and each must be satisfied for an interdependency relationship to exist. They are domestic support and personal care, financial support, living together and a close personal relationship,” he said,

“Can an adult child and a parent be in an interdependency relationship? In the view of the ATO it seems highly unlikely as the ATO considers that an adult child and a parent cannot satisfy the ‘close personal relationship’ requirement of an ‘interdependency relationship’. The ATO seems to identify a ‘close personal relationship’ as being equivalent to a mutual commitment to having a shared life above and beyond that of a parent/child relationship.”

However, Hallinan questioned whether the ATO’s view is supported by the relevant legislation.

He said the term “interdependency relationship” is defined in section 302-200 of the Income Tax Assessment Act 1997 and has an identical definition in the Superannuation Industry (Supervision) Act 1993. 

“The Tax Act determines the taxation treatment of a death benefit while the SIS Act determines whether the death benefit can be paid as an income stream”  he said.

Hallinan said historically, the term “interdependency relationship” was introduced by the Superannuation Legislation Amendment (Choice of Superannuation Funds) Act 2004 (No 102/2024) and was originally introduced into the 1936 Tax Act (as s27AAB).

When the superannuation provisions were transferred to the 1997 Act, that section became s302-100 and there have been no material amendments to the term since 2004. 


Furthermore, he added, the Income Tax Amendment Regulations 2005 (No 7) amended the Income Tax Regulations by introducing Regulation 8A which provides a shopping list of matters which should be taken into account (where relevant) to determine the existence of an “interdependency relationship”. 

Following the relocation of the superannuation provisions from the 1936 Act to the 1997 Act, Regulation 8A was enacted (without material alternation) as Regulation 302-200.1 of the Income Tax Assessment (1997 Act) Regulations.

The definition contains four requirements mentioned previously and each of these requirements will be considered using the situation of an adult child providing care to a parent.

The requirement of having a “close personal relationship is usually the most difficult to satisfy in an adult child/parent situation, Hallinan said. 


“The difficulty is twofold. First, the expression has no precise or generally accepted content.  Secondly, the difficulty of direct proof and the consequent reliance of inferences from the conduct of the adult child and parent,” he said.

He continued that the explanatory memorandum to the legislation, which originally introduced the term “interdependency relationship”, describes a “close personal relationship” as one “that involves a demonstrated and ongoing commitment to the emotional support and well-being of the two parties” and that the indicators of a close personal relationship may include “(i) the duration of the relationship; (ii) the degree of mutual commitment to a shared life; and (iii) the reputation and public aspects of the relationship (such as whether the relationship is publicly acknowledged”. 

“Significantly, the explanatory memorandum provides that ‘the above indicators are not an exclusive list and none of them are required for a close personal relationship to exist’,” he said.

Additionally, he said, the explanatory statement for the regulations which introduced the predecessor to regulation 302-200.01 stated that “Generally speaking, it is not expected that children will be in an interdependency relationship with their parents.”

“While the concept of ‘interdependency relationship’ was clearly introduced in 2004 to cover same sex relationships where the relationship was marriage-like the concept has a broader application which is clearly evidenced by the express statement that the three marriage like indicators are not an exclusive list and that none are required for a close personal relationship to exist.

“Further, the shopping list of factors, many of which are plainly features of marriage like relationships, are to be taken into account, but only where relevant.  Finally, the expressed recognition that a child/parent relationship could constitute an interdependency relationship (albeit the relationship would be exceptional in nature) clearly shows the concept is not limited to marriage-like relationships.”

Hallinan said in many PBRs on whether an adult child and their parent are in an interdependency relationship, the “close personal relationship” requirement is held to be not satisfied because there was no mutual commitment to having a shared life above and beyond that of a parent/child relationship. 

“With respect, there seems to be an established view of the ATO that for a ‘close personal relationship’ to exist there must be a marriage like relationship.  If there is a marriage-like relationship between two individuals, then it can usually be inferred that a close personal relationship will exist.  However, the issue is not whether a marriage-like relationship exists, but whether the relationship which exists between the two parties is a close personal relationship,” he said.

“If a relationship between an adult child and the parent satisfies the ‘living together’ and the ‘domestic support and personal care’ requirements, then this would take the relationship beyond the normal adult child/parent relationship. 

“Further, if the adult child has significantly altered his or her life by relocating residences, putting their employment or career or personal life on hold to care for the parent, this would clearly establish a close and personal relationship given the personal cost to and sacrifice borne by the adult child.  While the relationship will be terminated upon the death of the parent and so, the relationship is not of an indefinite duration or even of a long duration, while the relationship exists it will be of an exceptional nature.”